Rental Property Tax Strategy for San Diego Landlords: Before Year-End 2026
Home / Rental Property Tax Strategy for San Diego Landlords: Before Year-End 2026
Rental Property Tax Strategy for San Diego Landlords: Before Year-End 2026
Here is a number that should get every landlord’s attention: the difference between an owner who understands rental tax strategy and one who does not can easily be $5,000 to $15,000 per year, per property.
That is not a rounding error. That is the difference between a good investment and a great one, and much of it comes down to decisions you can still make before December 31.
Rental property offers tax advantages that few other investments can match. Depreciation lets you write off the cost of a building that may be growing in value. Mortgage interest, property taxes, and operating expenses reduce your taxable income further. And strategies like the 1031 exchange let you defer capital gains potentially indefinitely. But none of these benefits are automatic. They require knowing what is available and keeping the records to claim it.
With the fourth quarter here, now is the time to get organized. This article walks through the rental tax strategies San Diego landlords should understand before year-end 2026. One important note up front: we are property managers, not tax advisors, so treat this as an educational starting point and confirm everything with a qualified tax professional before acting.
Depreciation: The Deduction Most Landlords Underuse
Depreciation is the single most powerful and most misunderstood rental tax benefit, so it is worth understanding first.
The concept is straightforward but counterintuitive. The IRS lets you deduct the cost of your rental building over 27.5 years, even while the property may be appreciating in value. You are writing off “wear and tear” on paper while the asset potentially grows in worth. For many landlords, depreciation alone can shelter $5,000 to $10,000 of rental income from taxes every year, with no cash outlay at all.
“We see it all the time in the San Diego market. Property in our area appreciates rapidly. That is the true beauty of the tax code, the IRS allows you to take deductions throughout the year for wear and tear, while your asset is building real world wealth and equity for your family.”
Billy Colestock, WeLease Co-Founder
Here is a critical warning that catches some owners: the IRS requires you to recapture depreciation whether or not you actually claimed it. In other words, skipping depreciation does not avoid the recapture tax when you sell, it just means you lose the annual deduction while still owing the tax later. Not taking depreciation is almost always a mistake.
Two ways to accelerate depreciation:
- Cost segregation study. This breaks your property into components, appliances, carpeting, fixtures, landscaping, and reclassifies them from the 27.5-year schedule into faster 5-, 7-, or 15-year categories. For higher-value properties, this can generate substantial first-year savings.
- Bonus depreciation. Under the One Big Beautiful Bill Act (OBBBA), 100% bonus depreciation was permanently restored, which pairs powerfully with a cost segregation study to unlock large first-year deductions on qualifying components.
What this means for you: Depreciation is a large, no-cash deduction that most landlords underuse. Not claiming it does not avoid the recapture tax later, so there is rarely a reason to skip it. For higher-value San Diego properties, ask a tax professional whether a cost segregation study could accelerate significant deductions, especially with 100% bonus depreciation restored.
The Everyday Deductions Landlords Miss
Beyond depreciation, a rental property generates a long list of deductible expenses, and landlords routinely leave money on the table by not tracking them carefully.
| Deductible Expense | Notes |
|---|---|
| Mortgage interest | Often the largest single deduction |
| Property taxes | Fully deductible on Schedule E for rental property |
| Insurance | Landlord, hazard, and liability policies |
| Repairs and maintenance | Deductible in the year incurred (see repair vs. improvement below) |
| Property management fees | Fully deductible |
| Utilities you pay | Water, trash, gas, or electric you cover |
| Professional services | Legal, accounting, tax prep |
| Travel and mileage | Trips to the property for management purposes |
| Home office | If you manage rentals from a dedicated space |
| Advertising and leasing | Listing costs, screening fees |
Source: WeLease Team, updated 2026. Deductibility depends on your specific situation; confirm with a tax professional.
The pattern here is simple: nearly every legitimate cost of operating a rental is deductible, but only if you have the records to prove it. Owners who track expenses casually end up guessing at tax time and almost always underclaim.
Yuliana, WeLease Operations Manager, on why records make the difference:
“This is where ‘document everything’ pays off directly in dollars. Every repair receipt, every mileage log, every management fee, every utility payment, if it is not recorded, most owners forget it by tax time and simply lose the deduction. We keep clean, organized records on every property all year long, so when tax season comes there is no scramble and nothing gets left on the table. The landlords who overpay at tax time are almost always the ones who did not document as they went.”
What this means for you: Nearly every cost of running a rental is deductible, but only with records to back it up. The landlords who capture the full benefit are the ones who document expenses all year, not the ones who reconstruct them in a panic each April. Good record-keeping is, quite literally, money.
Repairs vs. Improvements: A Distinction That Matters
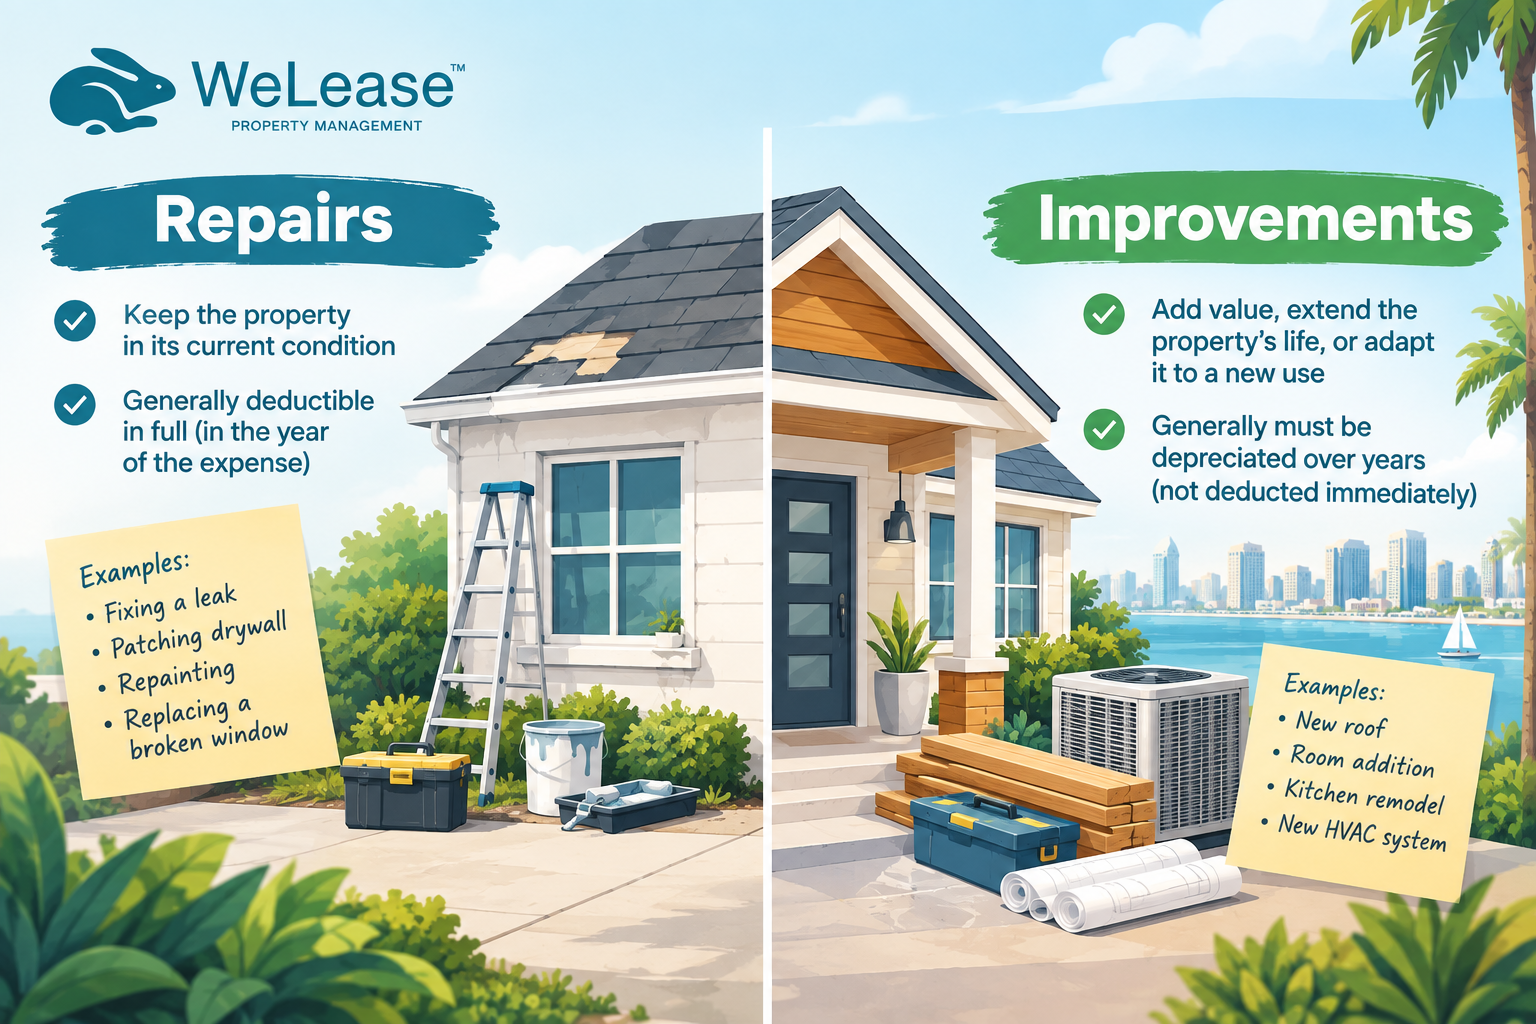
One of the most common and costly tax mistakes landlords make is confusing repairs with improvements. The difference has real tax consequences.
Repairs keep the property in its existing condition and are generally deductible in full in the year you incur them. Fixing a leak, patching drywall, repainting, replacing a broken window.
Improvements add value, extend the property’s life, or adapt it to a new use, and generally must be depreciated over years rather than deducted immediately. A new roof, a room addition, a full kitchen remodel, a new HVAC system.
Misclassifying the two is a frequent trigger for IRS scrutiny. Deducting a major improvement as a repair, in particular, can create problems in an audit. The distinction is not always obvious, which is exactly why professional guidance matters, and why keeping clear documentation of what work was done and why is so important.
When an owner considers improving their property, we always want to review the entire financial picture. That often times starts with understanding their goals. When considering improvements, tax benefits are a factor, but not the only one. The market and the owner’s goals are always equally important.
Yesenia Colestock, WeLease Co-Founder
What this means for you: Repairs are generally deductible now; improvements are generally depreciated over time. Getting the classification wrong, especially treating a big improvement as an immediate repair, invites IRS scrutiny. When the line is unclear, document the work carefully and ask a tax professional rather than guessing.
The Pass-Through Deduction: A Major Benefit Made Permanent
Here is a significant benefit that many landlords do not realize they may qualify for, and it was just made permanent.
The Qualified Business Income (QBI) deduction, often called the pass-through deduction, lets eligible landlords deduct up to 20% of their net rental income from their taxable income. Under the OBBBA, this deduction was permanently extended, removing the uncertainty that previously surrounded it.
The impact is real. For a landlord netting $30,000 a year in rental income, a full 20% QBI deduction is a potential $6,000 deduction, which at a 24% tax bracket is roughly $1,440 in tax savings, every year. Because most landlords operate through LLCs or as sole proprietors, understanding whether you qualify for the pass-through deduction is essential to lowering your effective tax rate.
Qualification depends on factors including your income level and whether your rental activity meets certain “trade or business” tests, including the QBI safe harbor rules. This is squarely a question for your tax professional, but it is one worth raising, because the benefit is substantial and now permanent.
What this means for you: The pass-through (QBI) deduction can shelter up to 20% of your net rental income and is now permanent. For many San Diego landlords operating through LLCs or as sole proprietors, this is one of the most valuable benefits available. Ask your tax professional whether you qualify, because the annual savings can be significant.
The 1031 Exchange: Deferring Taxes When You Sell
For landlords thinking about selling, one strategy stands above the rest for its wealth-building power: the 1031 exchange.
A 1031 exchange lets you sell an investment property and reinvest the proceeds into another like-kind investment property while deferring the capital gains tax and the depreciation recapture tax. Instead of losing a chunk of your proceeds to taxes at each sale, you keep the full amount working for you, allowing you to grow your portfolio faster.
1031 exchanges should not scare owners considering selling their current investment property. As your broker and partner in this exchange, it is our job to understand your goals and needs before placing the property on the market. We will work with you to understand the timing, and even in many cases have the replacement property lined up before any marketing begins.
Billy Colestock, WeLease Co-Founder
The numbers illustrate the power. Say you sell a rental for $400,000 with a $150,000 gain and $50,000 of accumulated depreciation. Without a 1031 exchange, you might owe roughly $30,000 in capital gains tax plus around $12,500 in depreciation recapture. With a 1031 exchange, you defer all of it, and you can keep deferring indefinitely through successive exchanges.
There is an important long-term angle here. Investors who “swap till they drop,” continuing 1031 exchanges throughout their lifetime, can pass properties to heirs who receive a stepped-up basis, which can eliminate the deferred taxes entirely. This is one of the most powerful wealth-building strategies in real estate.
The catch: 1031 exchanges have strict timelines and rules, and generally require a qualified intermediary. You must identify replacement property within 45 days and close within 180 days. These deadlines are unforgiving, so a 1031 must be planned before you sell, not after.
This connects directly to the hold-or-sell thinking we explored in neighborhood cycles: when to hold, improve, or exit. If selling is on your horizon, the tax strategy should be part of the decision from the start.
Billy Colestock, WeLease Co-Founder and REALTOR®, on thinking like an investor at tax time:
“The biggest mistake I see is owners treating taxes as something that happens to them in April instead of something they plan around all year. A serious investor thinks about the tax consequence before making a move, not after. If you’re even considering selling, you plan the 1031 before you list, because once you’ve sold without one, that door is closed. Depreciation, the pass-through deduction, a well-timed exchange, these aren’t loopholes, they’re the tools that separate a decent real estate return from a genuinely great one. You just have to use them deliberately.”
What this means for you: A 1031 exchange can defer both capital gains and depreciation recapture when you sell, keeping your full proceeds working and letting you build wealth faster. But the timelines are strict and must be planned before you sell. If selling is anywhere on your horizon, involve a tax professional and a qualified intermediary early.
Getting Organized Before Year-End: A Practical Checklist
The fourth quarter is the time to prepare, because some tax moves must happen before December 31. Here is a practical starting point.
- Gather and organize all expense records for the year: receipts, invoices, mileage logs, management statements, and utility bills.
- Confirm you are claiming depreciation, and ask your tax professional whether a cost segregation study makes sense for your property.
- Review the repair vs. improvement classification of any major work done this year.
- Ask about the pass-through (QBI) deduction and whether you qualify.
- If you are considering selling, discuss a 1031 exchange with a tax professional and qualified intermediary before listing.
- Consider timing. Some landlords accelerate deductible expenses into the current year or defer income where appropriate. Your tax professional can advise on timing moves specific to your situation.
- Separate your books. Keep rental finances distinct from personal finances, which supports both compliance and deductions.
The landlords who capture the full tax benefit of their rentals are the ones who treat this as a year-round discipline rather than an April scramble. Good property management supports this directly, because organized records, documented expenses, and clean financial statements are a natural byproduct of professional management.
What this means for you: Year-end is the window to get organized and make the moves that must happen before December 31. Gather your records, confirm your depreciation, review your classifications, ask about the pass-through deduction, and plan any sale-related strategy early. The owners who prepare in Q4 capture benefits the April-scramble crowd misses.
Talk to Yesenia and Billy
To be clear, WeLease provides property management, not tax advice, and every landlord’s tax situation is different. But good management and good tax outcomes go hand in hand, because organized records, documented expenses, and clean financials are exactly what make tax season straightforward and deductions easy to claim.
At WeLease, we keep meticulous, organized records on every property we manage, which means our owners head into tax season prepared rather than scrambling. We work alongside your tax professional by providing the clean documentation that makes claiming every legitimate deduction simple.
If you want your rental managed in a way that keeps you organized and ready for tax time all year long, reach out.
www.WeLeaseUSA.com | (619) 876-0753
Key Takeaways
- The difference between a landlord who understands rental tax strategy and one who does not can be $5,000 to $15,000 per year, per property. Much of it depends on decisions made before year-end.
- Depreciation lets you deduct the building’s cost over 27.5 years even as it appreciates, often sheltering $5,000 to $10,000 a year. You owe recapture tax whether or not you claim it, so rarely skip it.
- Cost segregation and 100% bonus depreciation (permanently restored under the OBBBA) can accelerate significant first-year deductions on qualifying components.
- Nearly every cost of operating a rental is deductible, mortgage interest, property taxes, insurance, repairs, management fees, and more, but only with records to prove it.
- Repairs are generally deductible now; improvements must be depreciated. Misclassifying them, especially treating improvements as repairs, invites IRS scrutiny.
- The pass-through (QBI) deduction lets eligible landlords deduct up to 20% of net rental income and is now permanent under the OBBBA.
- A 1031 exchange defers capital gains and depreciation recapture when you sell, but has strict timelines and must be planned before listing.
Frequently Asked Questions
What tax deductions can San Diego landlords claim on a rental property?
Landlords can generally deduct mortgage interest, property taxes, insurance, repairs and maintenance, property management fees, utilities they pay, professional services, travel and mileage for management, advertising, and depreciation of the building. Nearly every legitimate cost of operating the rental is deductible, but you need organized records to claim them. Confirm your specific deductions with a tax professional.
How does rental property depreciation work?
The IRS lets you deduct the cost of a residential rental building over 27.5 years, even while the property may be appreciating. This can shelter $5,000 to $10,000 of income a year with no cash outlay. Importantly, the IRS requires depreciation recapture when you sell whether or not you actually claimed the deduction, so skipping depreciation usually just costs you the annual benefit while still owing the tax later.
What is a 1031 exchange and should I use one?
A 1031 exchange lets you sell an investment property and reinvest the proceeds into another like-kind investment property while deferring capital gains tax and depreciation recapture. It can be a powerful wealth-building tool, letting you grow your portfolio faster and even pass properties to heirs with a stepped-up basis. However, it has strict timelines (45 days to identify, 180 days to close) and requires a qualified intermediary, so it must be planned before you sell. Consult a tax professional.
What is the pass-through deduction for landlords?
The Qualified Business Income (QBI) deduction, or pass-through deduction, lets eligible landlords deduct up to 20% of their net rental income from taxable income. It was made permanent under the One Big Beautiful Bill Act. For a landlord netting $30,000 a year, that could be a $6,000 deduction. Qualification depends on income and whether your rental meets certain tests, so ask your tax professional whether you qualify.
Do I need to keep receipts for rental expenses?
Yes, and it directly affects how much you save. Nearly every rental deduction requires documentation to claim and to defend in an audit. The IRS can audit rental returns up to three years after filing (six years if income is significantly understated). Keep organized records of all receipts, invoices, mileage, management statements, and financials throughout the year. Owners who track expenses casually almost always underclaim at tax time.
Disclaimer: This article is intended for general informational and educational purposes only and does NOT constitute tax, legal, or financial advice. WeLease provides property management services, not tax advisory services. Tax laws are complex, change frequently, and apply differently to each individual situation. Always consult a qualified tax professional or CPA before making any tax-related decisions. For property management guidance, contact us at www.weleaseusa.com.
Reviewed by Billy Colestock, Co-Founder & Executive Officer, WeLease | REALTOR® DRE# 01771188
Billy Colestock brings over 20 years of real estate experience to his leadership role at WeLease Property Management. As a licensed REALTOR® and Co-Founder of WeLease, he is a trusted voice in the San Diego real estate community and regularly leads educational sessions at the San Diego Association of REALTORS® (SDAR) on topics including evictions, tenant screening, maintenance, and housing regulations. He is a member of the National Association of REALTORS® and the California Association of REALTORS®, and serves as President of his HOA. WeLease has been recognized as San Diego’s Best Property Management Company by the San Diego Union-Tribune (Winner 2022, 2024; Finalist 2023, 2025) and named a Top 10 Property Management Company in El Cajon and Chula Vista by Expertise.com in 2026. WeLease Credentials: NARPM® Member, BBB Accredited, MLS Participant, Equal Housing Opportunity. DRE: 02047533.
Ivana M. Janakieva is a Property Management Marketer and SEO Content Manager who turns confusing real estate jargon into practical, actionable advice. She’s the type who reads maintenance reports like morning news and can make lease agreement clauses sound (almost) fun. With years of experience writing about everything from tenant turnover and landlord-tenant laws to climate risks and curb appeal ROI, Ivana creates content for people who want straight answers about protecting and profiting from their most valuable asset, their property.